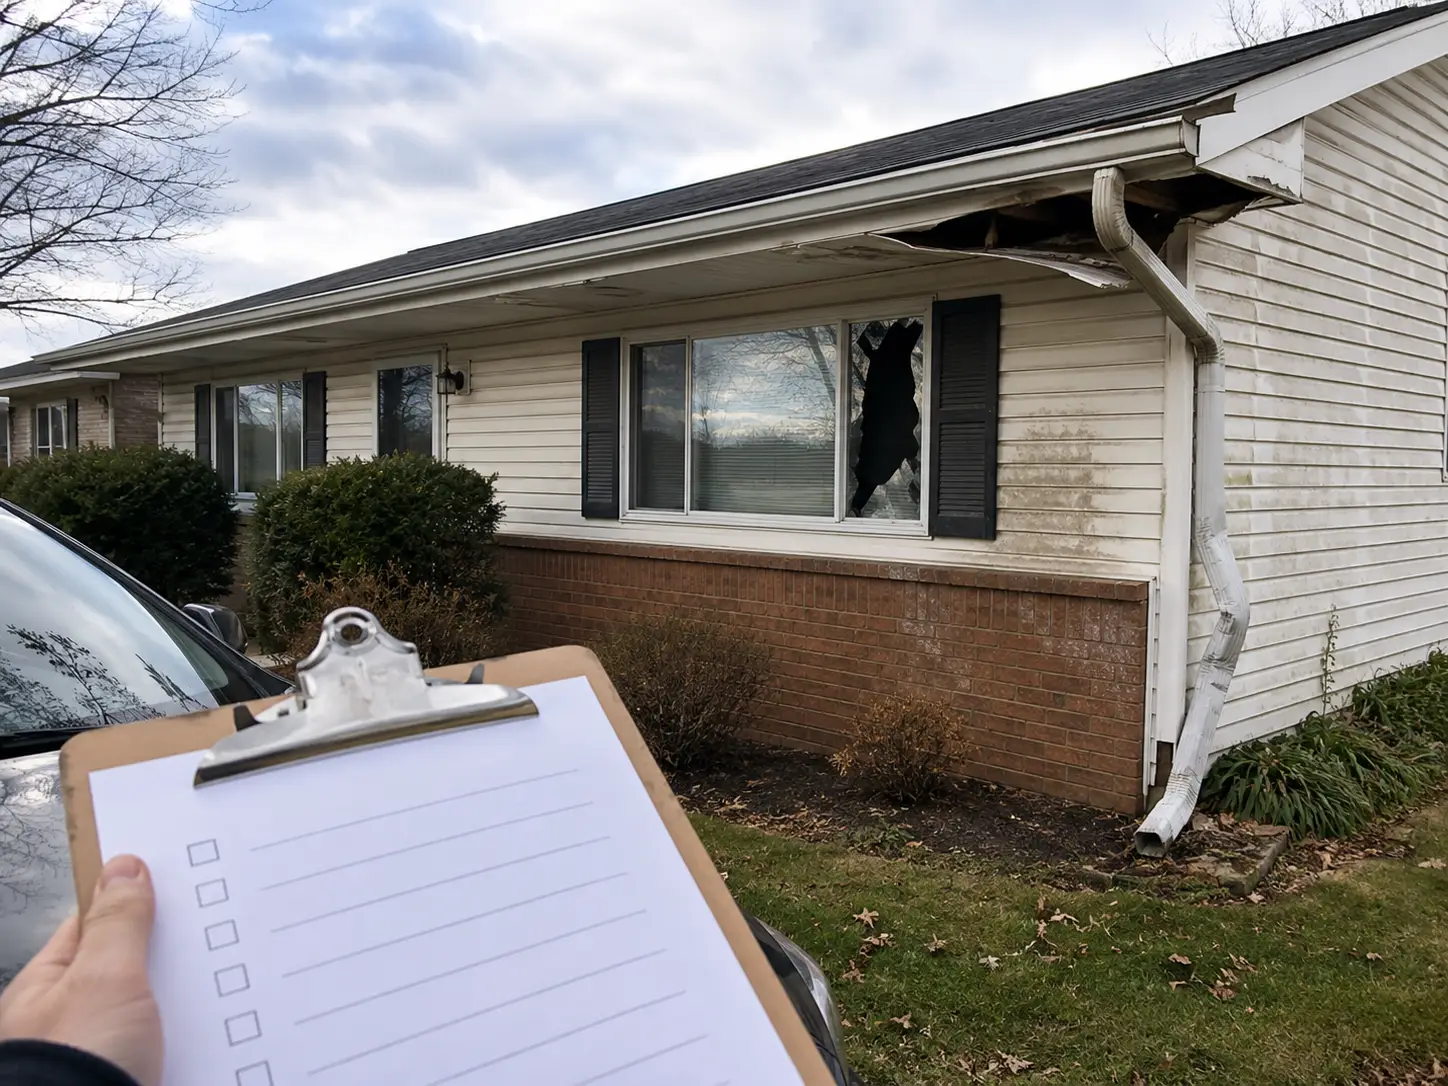
Use this checklist during your first insurance conversation and update it as information becomes available. Contact your insurer or agent promptly about reporting requirements; do not wait to complete every item or obtain a contractor report before asking for guidance. Safety and necessary temporary protection come first.
Information to have available
- Your property address and policy information, if readily available.
- When you first noticed the damage and the relevant weather or incident details you actually know.
- A short list of affected areas: roofing, siding, gutters, windows, and interior rooms.
- Whether water is still entering or an opening needs urgent protection.
- Photos you can obtain safely and any temporary-work receipts.
- Previous repairs or known concerns that may be relevant.
Do not guess a date, cause, or quantity to fill a gap in the record. State what remains uncertain and ask how to provide further information later.
Questions for the insurer
- How should I report the loss, and which deadlines or follow-up requirements apply?
- What evidence do you need now, and what can follow after inspection?
- How should urgent protection, damaged items, and permanent repair planning be handled?
- Will there be an inspection, and how should I prepare for it?
- Which deductible, limits, exclusions, or settlement conditions are relevant to the review?
- Who is my contact, and how can I request written clarification?
The answers depend on your policy and circumstances. A general checklist or contractor estimate cannot determine coverage.
Notes to keep after each conversation
Record the date, contact name, claim or reference number, documents requested, agreed next steps, and any stated deadlines. Keep copies of messages and submissions. Ask for confirmation when instructions are unclear or differ from an earlier conversation.
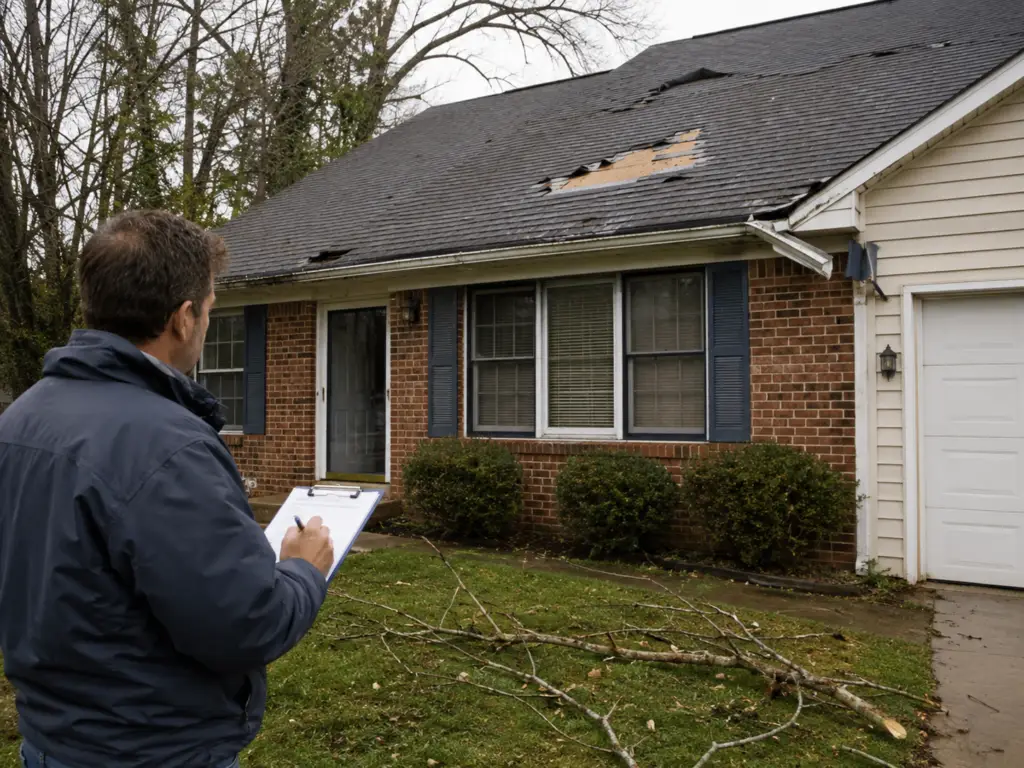
Information to request from the contractor
Ask for observed findings, labeled photos, inaccessible areas, and a written repair scope. The estimate should distinguish the agreed work from allowances, optional work, and concealed conditions. If more than one exterior component is involved, identify the shared junctions and who will coordinate them.
When the contractor estimate and insurer assessment differ, compare the specific work described and ask each party to explain the difference. Do not assume that a higher or lower total means the scopes are equivalent.
Keep the repair agreement clear
Understand the work, payment obligations, change process, and warranty terms before agreeing to a project. Ask what happens if the insurer’s decision differs from your expectation. Keep claim correspondence alongside the contract without treating them as the same document.
Useful next steps
Our storm claim sequence includes official Virginia, Maryland, and DC consumer resources. For a safe record of the building condition, use our exterior observation checklist.
USA Storm Roofing can assess exterior concerns and prepare repair estimates across our listed service areas. Contact the team with your address and affected areas. We can explain proposed work and documented findings; we do not guarantee an insurance settlement.